
Purchase taxes: start with the right scenario
Before budgeting, distinguish a resale home —normally subject to transfer tax— from a developer's first transfer, which in VAT territory must be assessed for VAT and, where relevant, stamp duty. A business seller or special transaction can require different treatment.
No single Basque transfer-tax amount is shown: Álava, Bizkaia and Gipuzkoa use foral rules, and the buyer's and property's conditions require checking.
No single amount: Álava, Bizkaia and Gipuzkoa have separate foral tax rules and tax authorities. Check the historic territory, rate and reliefs for this property and buyer.
ITP/AJD is foral: check the rules and filing for the historical territory where the property lies, not a common-regime regional table. The actual filing depends on the facts and rules in force when tax arises.
The tax base and valuation checks here follow foral rules. Request cadastral or land records from the relevant foral authority and confirm the applicable valuation: the Spanish state Cadastre does not cover the Basque Country or Navarre. Budget separately for notary, registration, financing and later ownership costs.
State Cadastre: territorial scope · Bizkaia foral cadastre (example; confirm the territory)
Calculate for your price and circumstances: purchase-cost calculator.
What to check in this region
Territorial check
For tourist use, check the Basque register and compliance with municipal, housing and owners' association rules.
Use and permissions
First identify the historical territory—Álava, Bizkaia or Gipuzkoa—and municipality; there is no single tax authority or return for all Euskadi.
Property and historical territory
Confirm address, municipality and historical territory from title and foral cadastral reference before seeking a foral tax calculation. Also compare advertised uses and outbuildings with physical and municipal records.
Request a current Land Registry extract, a record from the historic territory's foral cadastre, deed and building-work history; for flats add owners' association papers. The municipality should confirm planning and uses where they affect the purchase. A plan, registration or photograph alone does not establish planning legality.
Areas and local decisions
A region is neither a single market nor a single planning regime. These areas raise different questions; the answer depends on the plot, building, municipality and intended use.
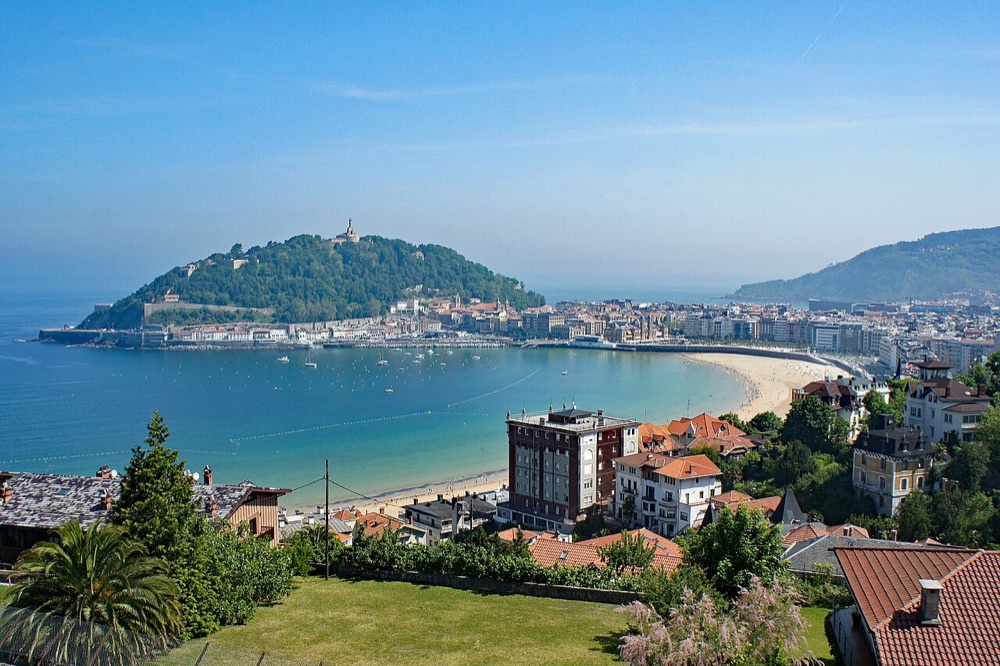
Donostia/San Sebastián and Gipuzkoa coast
Tourist use requires specific regional, municipal and building checks. Use the relevant Gipuzkoa foral tax regime rather than a generic mainland figure. For coastal homes, review coastal constraints; for older buildings, maintenance and major works. Establish cost and intended-use feasibility before offering.
View local entryBilbao, Getxo and Bizkaia coast
Distinguish Bizkaia foral taxes and the property's municipal rules. For buildings awaiting rehabilitation, obtain resolutions and major-work budgets. Near the estuary or coast, check location-specific constraints. For commercial conversions, establish compatibility and housing requirements before treating the offer as a completed home.
View local entryVitoria-Gasteiz and Rioja Alavesa
Tax review must use Álava and the transaction type. For historic or rural homes, check protection, annex status and permitted uses. If land or vineyard-related activity is included, define the assets, rights and agreements transferred: this differs from buying only a home.
View local entryIf you plan to live here
If you move to the Basque Country, establish from the outset whether the property is in Álava, Bizkaia or Gipuzkoa. The competent Foral Treasury for the purchase depends on the historical territory, not on one region-wide tax table; identify the municipality responsible for registration and planning as well. A home in Bilbao, Vitoria-Gasteiz or San Sebastián may face different use and building restrictions, so any tourist-letting proposal needs an address-specific check. Immigration residence depends on your own circumstances and nationality. Do not confuse paying a transaction tax there with becoming tax resident: review time spent, the centre of your interests and any treaty before planning your move.
Owning a Spanish home does not itself grant a right of residence or determine tax residence. If you move to Spain, coordinate immigration documents, local registration where applicable, healthcare cover and tax timing with your personal circumstances. Check utilities, actual vacant possession and key handover before planning the move.
If you are an EU citizen staying longer than three months, check the applicable registration requirement; if you are not an EU citizen, identify the appropriate stay or residence route in advance. Municipal registration, an NIE, home ownership and tax residence are distinct matters. Budget for local property tax, owners' association charges, insurance, utilities and possible non-resident income tax while you remain a non-resident.
AEAT: individual tax residence · Spanish administration: EU citizens' residence · Migration Ministry: living in Spain
Hypothetical example
Example: a couple buying in Donostia uses a tax calculator that treats the Basque Country as an ordinary common-regime region. Before finalising costs, they identify Gipuzkoa as the competent historical territory and check the particular transaction with its foral tax authority. They obtain a title extract and owners’ association papers and enquire locally about any intended holiday use. Price and deposit terms use a transaction-specific tax estimate, not a rate copied from Bizkaia, Álava or Madrid. The tax authority and municipality answer different questions; neither check replaces the other.
The example frames useful questions; it does not describe a real property or replace municipal enquiries or a technical inspection.
Continue with your transaction
Official sources and scope
- Gobierno Vasco · Tourist register
- Gobierno Vasco · Tourism procedure
- Hacienda Foral de Bizkaia · Transfer tax and stamp duty
- Colegio de Registradores · Land Registry
- Basque Government · three foral tax authorities
- Administración General del Estado · Residence of EU citizens
- AEAT · Individual tax residence
General information prepared with AI assistance and checked against the linked sources. Professional legal review of this editorial content is pending. The rules and documents for the individual transaction determine the next steps.